Farm policies work differently
Farm and ranch policies often schedule each outbuilding with its own limit, and many pay actual cash value rather than replacement cost on older structures. Coinsurance clauses may apply. Some buildings are covered for a short list of named perils rather than all risks. Those details affect both what is owed and how the appraisal award should be written.
Common farm and ranch disputes
- Steel panel damage from hail, with arguments over cosmetic versus functional dents and panel availability.
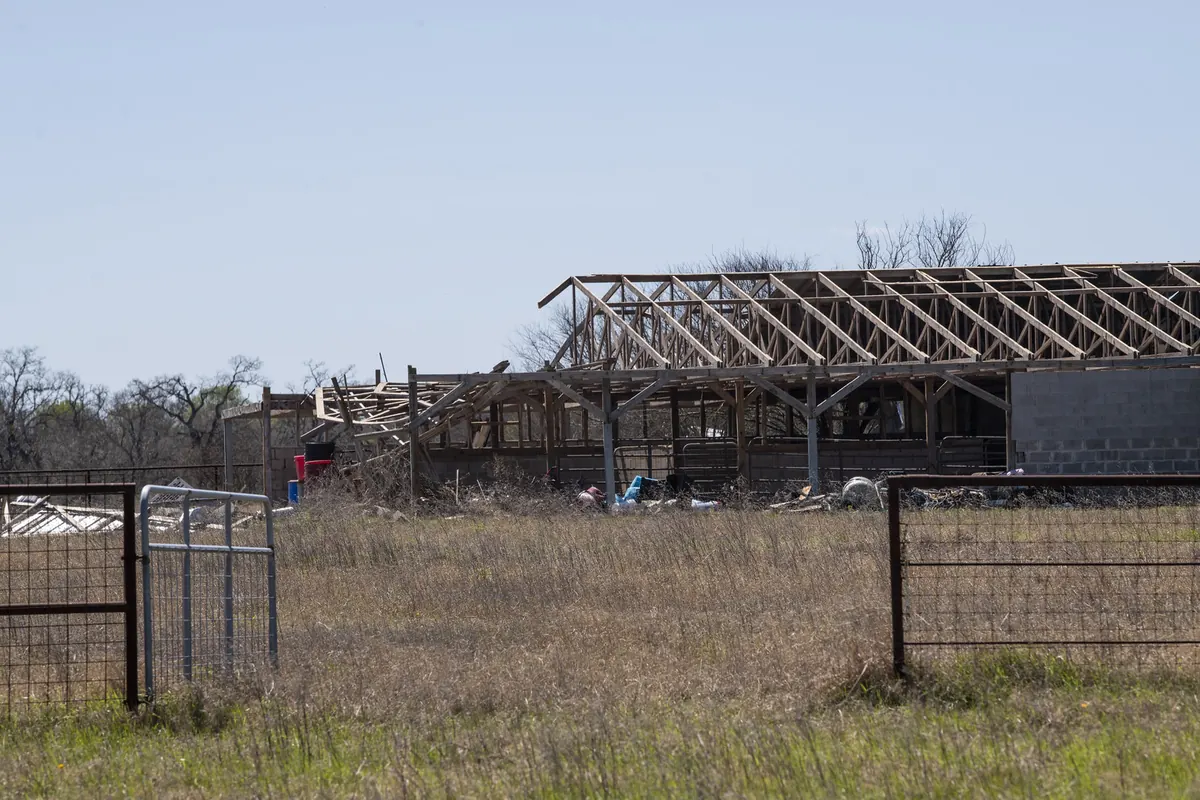
- Racked or twisted framing in pole barns after high wind, which can require rebuilding rather than re-sheeting.
- Snow-load collapse of machine sheds and livestock buildings.
- Grain bins and dryers dented or displaced, along with augers and electrical equipment.
- Overhead and sliding doors that no longer operate after wind damage.
- Depreciation applied heavily to well-maintained older buildings.
How we value rural buildings
We measure each structure, note framing type and spacing, identify panel profiles and gauges, and price replacement with the post-frame and steel building costs rural contractors actually charge, including travel to remote sites. When a building is scheduled at a limit that looks low, we flag it so you understand how the policy limit and coinsurance could affect the final payment.
Frequently asked questions
My policy pays ACV on outbuildings. Is appraisal still worth it?
Possibly. ACV is still based on replacement cost minus depreciation, so a higher replacement cost and fair depreciation both matter.
Do you value livestock or crop losses?
No. We focus on buildings and structures. Crop and livestock coverage usually involves separate policies and specialists.
How far do you travel?
Statewide. Many of our farm and ranch inspections are hours from the nearest city.